A fiscal-impact analysis for MCD7, LLC’s proposed data center campus in Limerick Township came under extensive questioning last week, with officials, attorneys, and nearby residents challenging assumptions about the project’s future value, workforce, and costs.
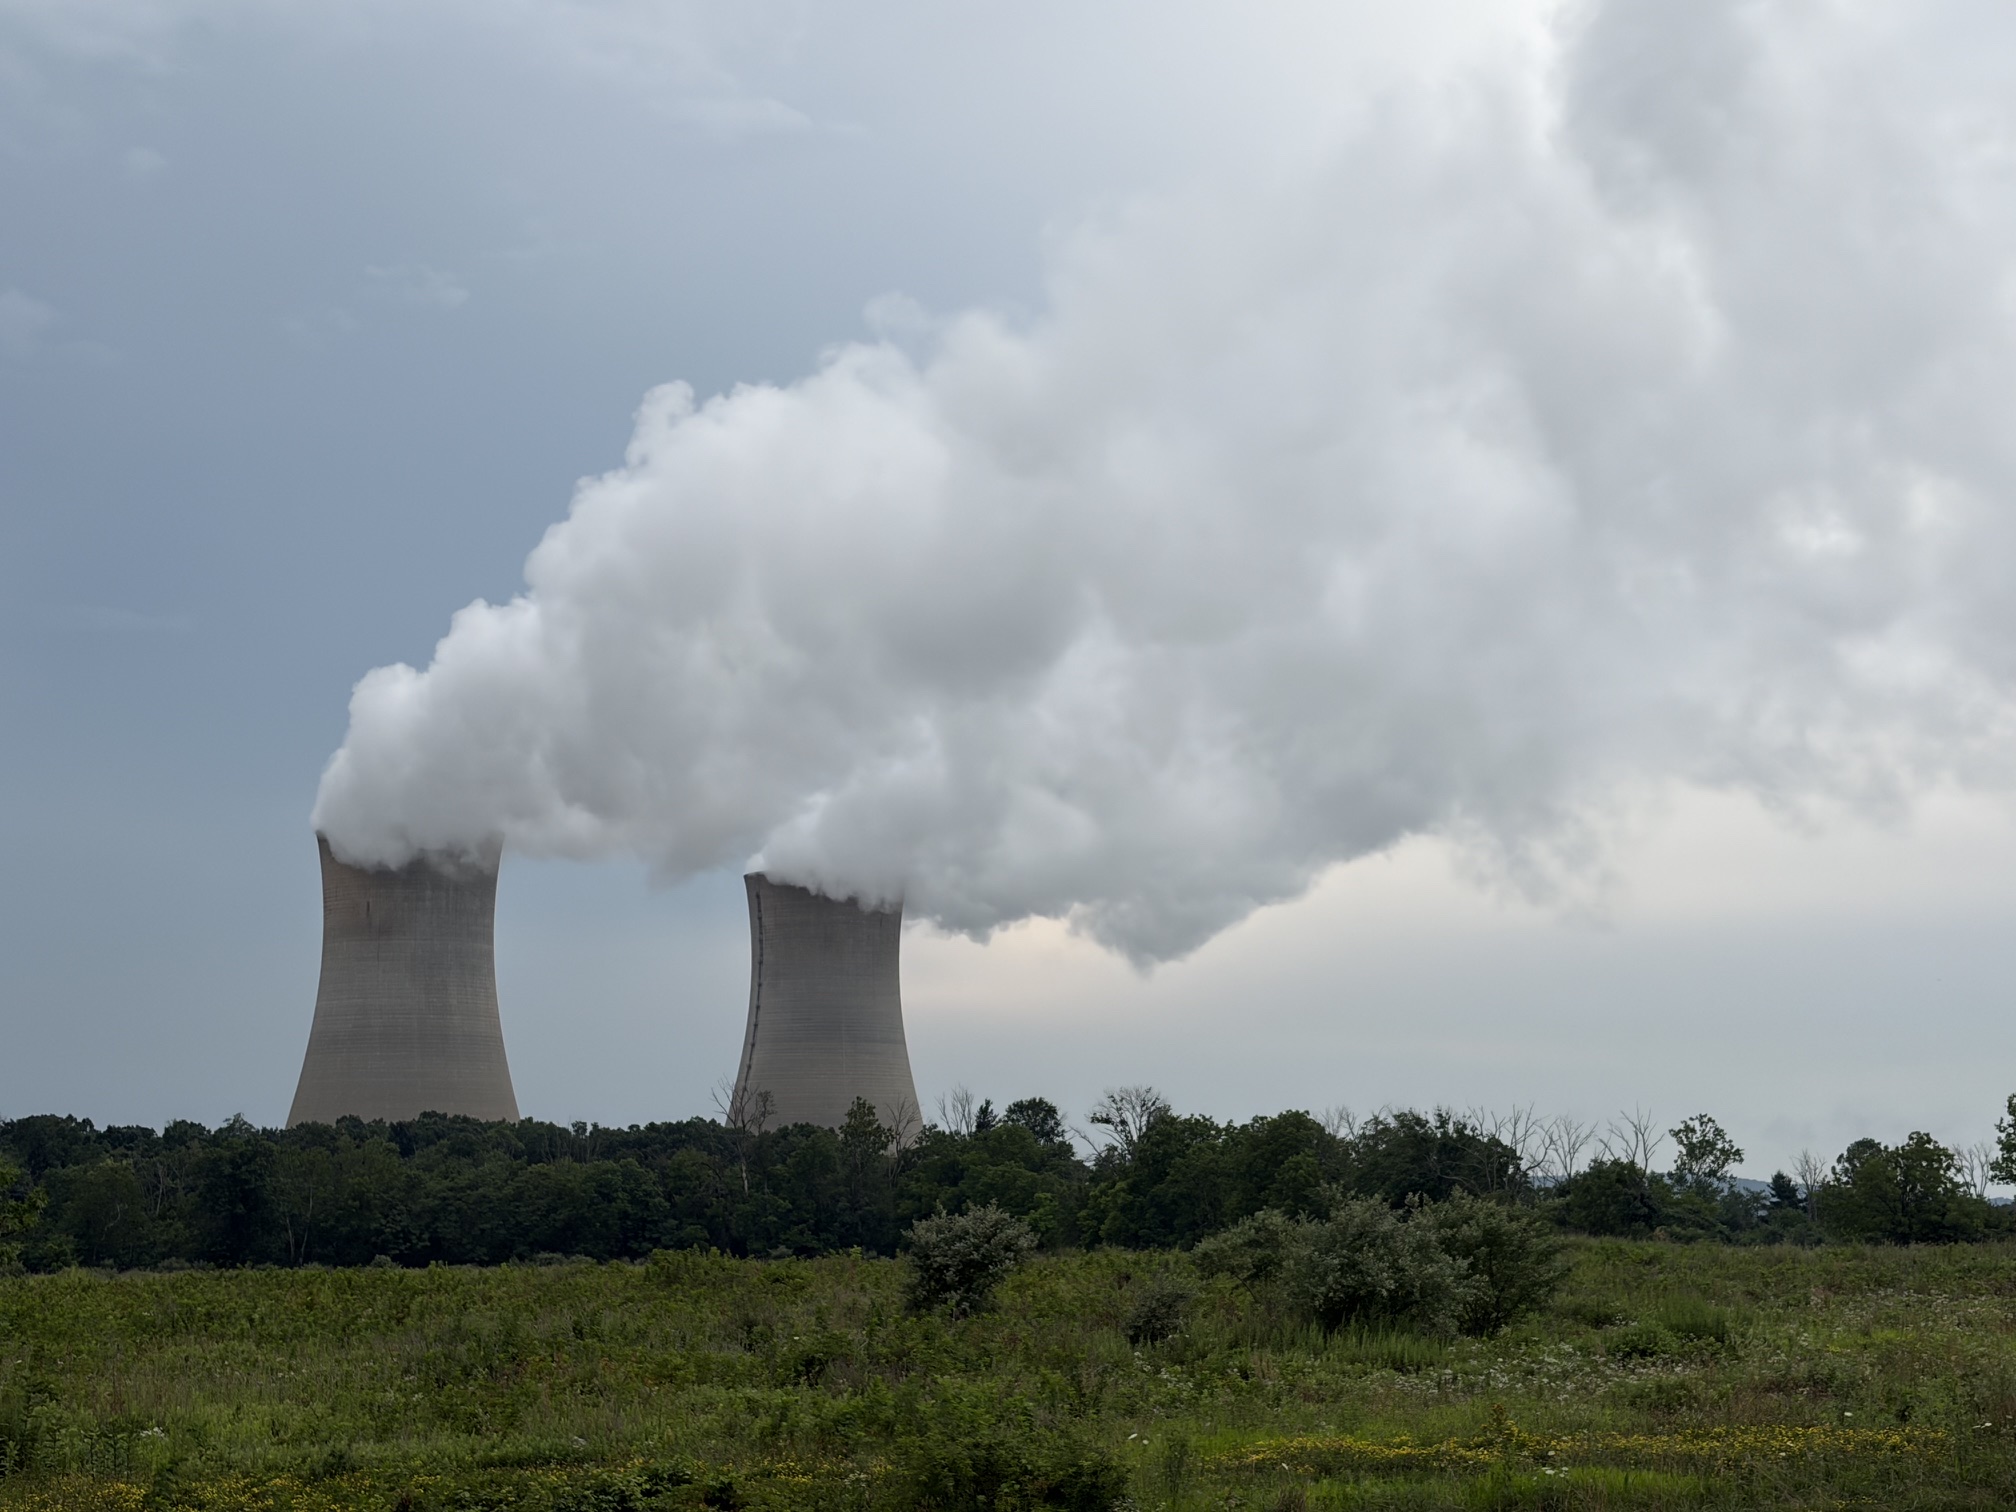
The September 8 hearing marked the sixth installment of the conditional use proceeding for the proposed campus, which would be built on approximately 191 acres near the Limerick Generating Station and Philadelphia Premium Outlets.
The analysis projects the development would generate a net annual fiscal benefit of roughly $3.39 million for Limerick Township and $33.39 million for Spring-Ford Area School District at full build-out.
But much of the evening focused on what went into those projections — and what did not.
$3.16 Billion Valuation Questioned
The projected tax benefits are heavily tied to the estimated future value of the development.
Erik Hetzel, the planner who prepared the fiscal-impact analysis, testified during the hearing after the Limerick Township Board of Supervisors voted to accept him as an expert witness. Hetzel’s qualifications had been questioned by the township’s attorney during the previous month’s proceedings.
Hetzel said the data center project could have a market value of roughly $3.16 billion at full build-out. The figure includes approximately 2.6 million square feet of data center space, along with a 32,000-square-foot logistics building and a 40,000-square-foot administration building.
The bulk of that valuation came from an assumption of $1,200 per square foot for the data center buildings. Hetzel testified that the $1,200 figure was provided by the applicant through its counsel and was used as an estimate of taxable construction and building improvements rather than an appraisal.
The assumption drew scrutiny in part because Hetzel acknowledged there were no comparable data center developments in Pennsylvania that he could use to establish a traditional set of real-estate comparables.
Instead, he relied on information from consultants working with the applicant as well as commercial real-estate and data-center industry sources.
Since the original report was prepared, Pennsylvania's Department of Community and Economic Development has issued a data center toolkit that uses a $1,000-per-square-foot benchmark for the construction and build-out portion of a hypothetical data center. A Tioga County assessment presentation cited a range of approximately $660 to $1,100 per square foot.
Hetzel testified that he ran the analysis using the state's $1,000 figure as a comparison. Under that assumption, the projected net benefit to Limerick Township would fall from about $3.39 million to $2.82 million annually, while the school district's projected net benefit would fall from about $33.38 million to $27.9 million.
He said the change would reduce, but not eliminate, the project's projected positive fiscal impact.
451 Employees vs. 300
One of the more notable discrepancies raised during the hearing involved the number of employees expected at the completed facility.
Hetzel's fiscal analysis assumes 451 full-time-equivalent employees will work at the development once it is operational.
He arrived at that figure using industry staffing ratios, including a general rule of one employee for every two megawatts of data center capacity. For the proposed 750-megawatt facility, that produced an estimate of 375 data center employees. He added 16 employees for the logistics building and 60 for the administration building.
But the attorney representing the township pointed to an American Water letter included as an applicant exhibit that identified 300 employees at full build-out.
Hetzel acknowledged that he had not used the 300-employee figure as the basis for his analysis. He said he considered his estimate conservative and explained that employee numbers affect both projected costs and earned-income-tax revenue.
Under questioning, Hetzel agreed that lowering the workforce assumption would reduce both the estimated costs and the earned-income-tax revenue, while leaving the project's real-estate tax revenue unchanged.
The 451 figure therefore matters primarily to the operational-cost and earned-income-tax portions of the fiscal analysis, rather than to the projected real-estate tax generated by the buildings.
What The Fiscal Analysis Does — And Doesn't — Include
The analysis was repeatedly described during the hearing as an assessment of recurring operating revenues and costs at full build-out, not a comprehensive assessment of every financial consequence of the project.
Hetzel testified that the analysis does not include capital budgets or one-time capital investments. Questions about potential specialized emergency equipment, for example, were outside the scope of the study.
There also is no separate fiscal analysis of the construction period. The report does not state when full build-out would occur, and the hearing included no construction-period fiscal projection.
Other items also were not included. The analysis does not account for water or wastewater costs, future tax appeals, or the three proposed electrical facilities and substations.
Hetzel also said the study did not attempt to measure indirect economic effects, such as increased spending in the local and regional economy, or ripple effects from additional development and population.
Emergency services presented a similar issue. The township's existing emergency-service expenditures are incorporated into the general operating-cost figure, but the analysis does not project whether the development would require an increased level of fire, EMS, or other emergency services. Hetzel said the model essentially assumes the development would have comparable service demands to the rest of the township.
The three proposed electrical facilities also were not included in the $3.16 billion valuation because Hetzel did not have an assessment or value for them.
Projected Benefit for the School District
The school district's projected benefit stood out in the analysis.
At full build-out, Hetzel projected approximately $33.39 million in net annual fiscal benefit for Spring-Ford Area School District. The figure includes projected real-estate, earned-income, and local-services tax revenue, with the final testimony putting total annual school-district revenue at $33,387,885.
The analysis, however, assigns zero operating costs to the school district.
The reason, Hetzel testified, is that the land use itself was assumed to generate no school-age children. As a result, the model did not assign additional school operating expenses to the development.
That assumption became another point of questioning.
Hetzel acknowledged that the analysis did not examine indirect or "ripple" effects on the school district, nor did it examine capital needs or other costs that might result indirectly from the project.
The $33 million figure represents a recurring annual projection based on the assumptions in the model, not a guarantee of future revenue.
Hetzel also said the projection is a snapshot based on an approximately $974.9 million assessed value, 2026 tax rates, and the 2026 assessment ratio. He acknowledged that tax rates and assessment ratios can change over time, and that the property's assessment could change through a reassessment or appeal.
Errors Acknowledged in the Analysis
The hearing also exposed errors in the original fiscal-impact report.
Hetzel testified that he corrected an error in his earned-income-tax calculation. The correction reduced the projected annual revenue to Limerick Township from $3,488,862 to $3,476,854 — a difference of about $12,000.
For the school district, the original figure of $33,447,925 was reduced to $33,387,885, a difference of roughly $60,000.
The EIT calculation received additional scrutiny later in the questioning. Based on the projected payroll and the assumed share of employees subject to the local tax, Hetzel acknowledged that the correct amount was about $60,000 rather than figures of approximately $72,000 or $120,000 that appeared in portions of the original calculations. He attributed the mistake to a spreadsheet error.
Hetzel maintained that the corrections did not change his overall conclusion that the project would produce a significant net positive fiscal impact.
Using the corrected figures, his final testimony put the projected annual net benefit at approximately $3.386 million for Limerick Township and $33.387 million for the school district. Montgomery County's projected benefit was about $5.76 million.
What's Next
The conditional use hearing will continue Thursday, October 1, at 6:30 p.m. at the Limerick Township building.
The applicant's attorney indicated that the next witness is expected to be someone other than Hetzel, meaning the fiscal-impact testimony is expected to give way to the next portion of the applicant's case. The applicant also reserved the possibility of recalling Hetzel if necessary.
For now, the fiscal analysis remains one piece of the larger conditional use proceeding — and last week's testimony left the board with a detailed look at both the potential tax revenue and the assumptions underlying the project's potential fiscal benefit.